Know Who to Lend to, How Much, and
What to Watch For
FinEye gives fintech lenders the analysis behind every credit decision. We read each applicant's bank statements, GST returns and credit bureau reports, work out their real income and obligations, flag the fraud a parser would miss, and send it back the same day — on every application, not a sample.

What Comes Back on an Applicant
Can They Repay?
How Much?
Bank Statement
ECS · Loan EMI
03 Oct · Not in the bureau report
NEFT · Shop rent
12 Mar · Recurring monthly




Who We Work With

Digital Lending Platforms
Personal and business loans underwritten end to end online.
.svg)
BNPL Providers
High volumes, small tickets, decisions in seconds.
.svg)
Lending Service Providers
Sourcing and underwriting against an NBFC or bank partner's credit policy.

Embedded Finance Teams
Credit offered inside another company's app or marketplace.
What Fintech Lending Looks Like

Thousands of Small Files
Ticket sizes are small and volumes are high, so cost and time per file decide whether the product works at all. Anything needing a person to read it does not survive contact with volume.
.svg)
Most Applicants are Thin-File
New-to-credit borrowers, gig workers and small businesses have little bureau history. What they do have is a bank account, and the account shows how money actually moves.
.svg)
.svg)
You Answer to a Partner's Credit Policy
Where an NBFC or bank holds the book, their credit team sets the rules and expects evidence behind every approval.
.svg)
.svg)
Fraud Arrives at Volume
Edited statements and borrowed documents get through because nobody checks a thousand files by hand.
What FinEye Analyses

Results reach you as structured data your credit rules can read, or as a report for anyone reviewing a file by hand.
What Sets Fineye Apart

We Analyse, We Do Not Just Extract
Most tools in this market read the PDF, hand back the transactions and leave the interpretation to you. FinEye does the analysis: obligations the applicant did not declare, funds moving between related accounts, income that does not match the stated business. You get findings, not a cleaner version of the input.
The Price Lets You Run it On Everything
FinEye costs less than the established players. Instead of reserving full analysis for files that already look risky, you can run it on every application and let the findings decide what needs a second look.
Questions
Lenders Ask
Income, average bank balance, EMI obligations, bounce history, categorised transactions, and flags for tampering and circular transactions. It arrives as structured data your credit rules can read, with a full report for manual review.
 What does FinEye send back?

Most stop at extraction and leave the reading to you. FinEye analyses the data, surfacing undeclared obligations, related-party flows and income that does not match the declared business. It is also priced below the established players, so it can run on every application rather than a selected few.
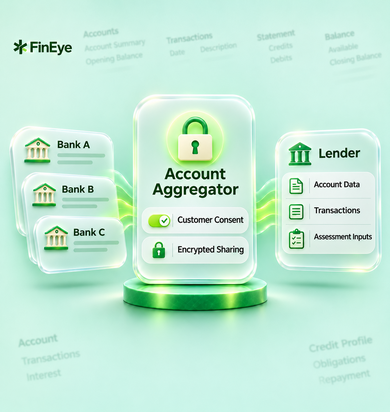
How is FinEye different from other bank statement analysis providers?Yes. Account Aggregator is part of the FinEye platform and is used by our bank and NBFC customers. For fintechs we usually start with uploaded statements, which fits an embedded journey.
Do you support Account Aggregator?Results come back as structured data, so they flow into your loan origination system and credit rules without anyone rekeying figures.
How quickly do we get results?Priced per analysis, below the established players in this market.
How much does it cost?Further Reading on
Digital Lending Risk
November 4, 2026 · 9 min read
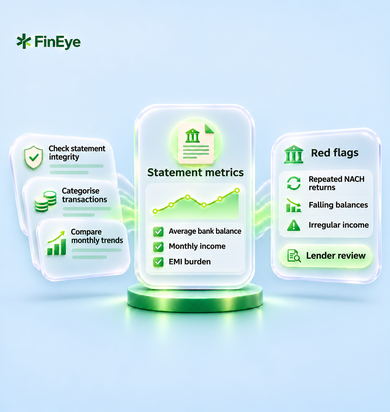
Bank Statement Analysis for Lending: Metrics, Methods, and Red Flags for Indian Lenders
Shivam Jadon
Digital Marketing Associate
November 4, 2026 · 9 min read
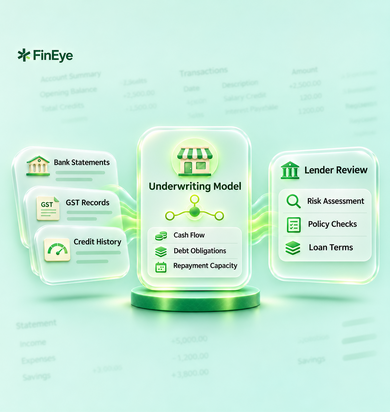
Credit Underwriting for MSME Loans: Process, Models, and the Data Behind Each Decision
Shivam Jadon
Digital Marketing Associate
November 3, 2026 · 12 min read
What is an Account Aggregator for Lenders? Understanding Meaning, Features & Benefits
Shivam Jadon
Digital Marketing Associate
 MSME Lending Intelligence Platform
- +91 96670 90342
- info@fineye.co
- Noida, Uttar Pradesh, 201301
Resources
Blogs
▶