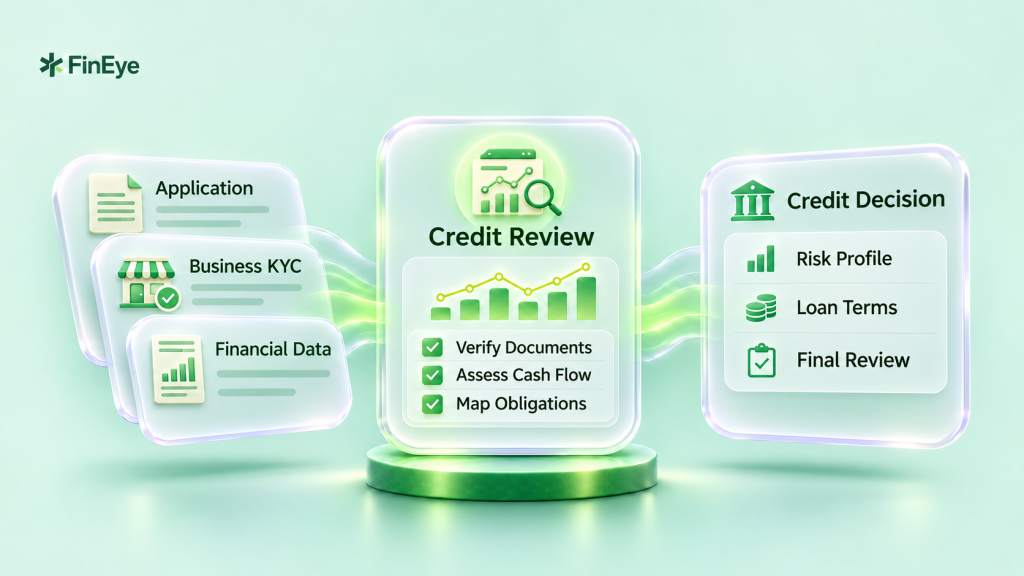
How Lenders Decide Who Gets a Loan? Understanding Credit Assessment for MSME Borrowers
shivam jadon
Featured
Quick Summary
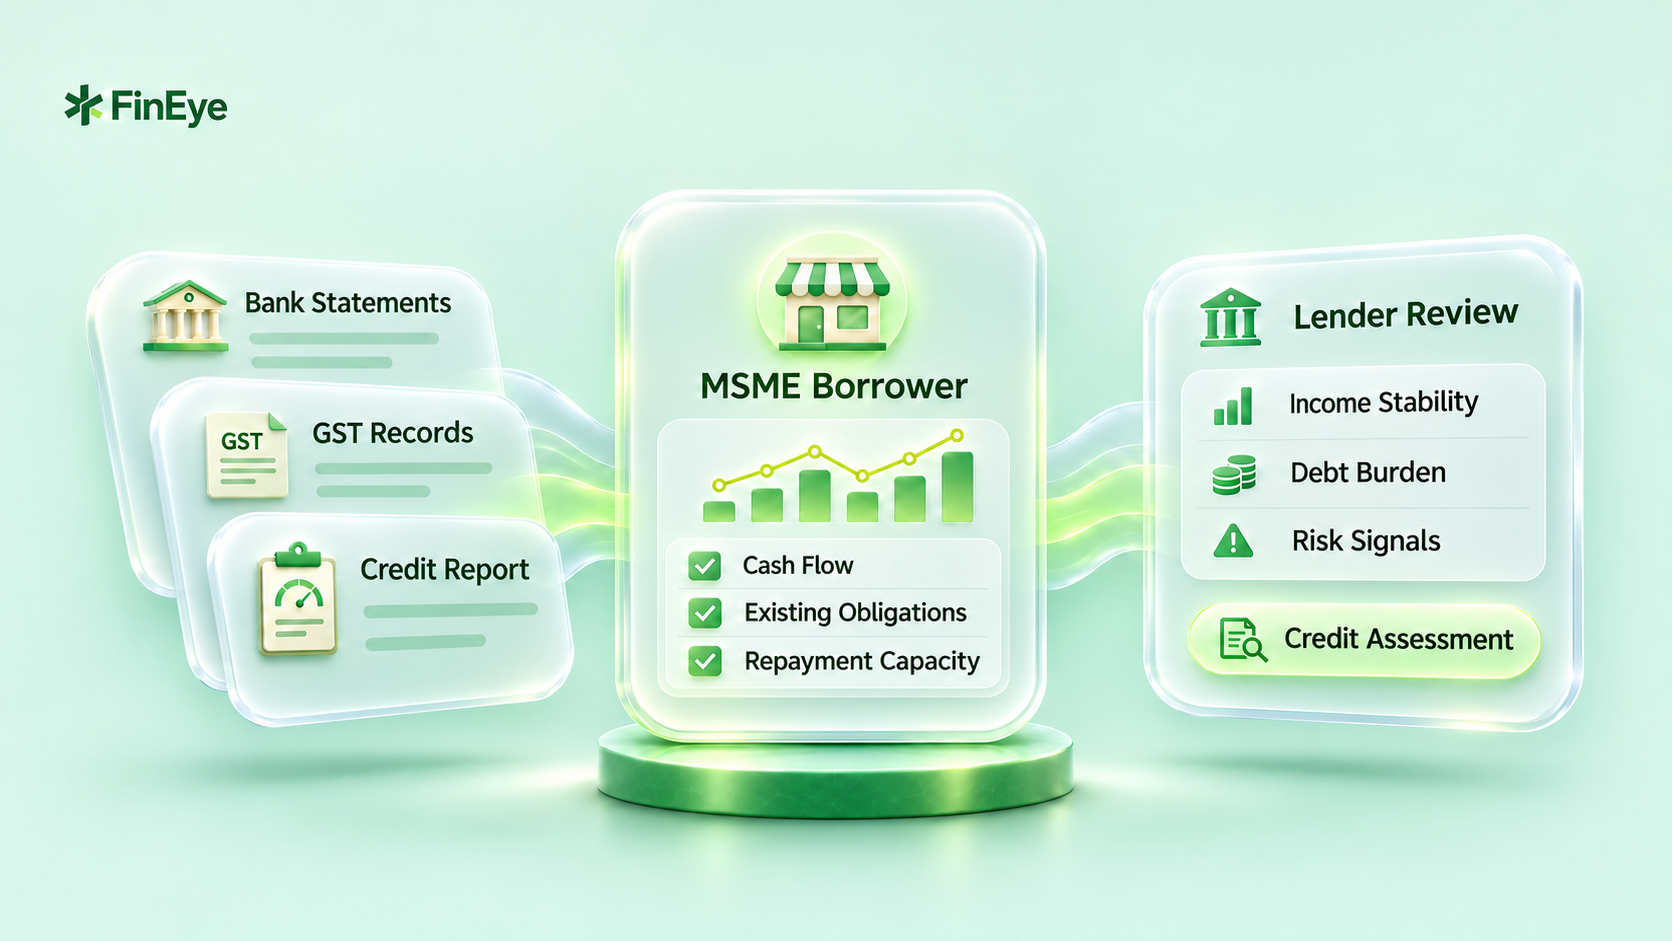
When you apply for a business loan, the lender is really asking two questions: can your business repay, and will it? To answer them, lenders study your cash flow, credit history, documents, and collateral. Today, they also lean heavily on digital records like GST returns and bank statements, not just paperwork and property.
You fill in the loan form, upload a stack of documents, and wait. A few days later, the answer arrives: approved, rejected, or “please send us one more thing.” But what actually happens on the lender’s desk in between? To find out MSME loan creditworthiness, let us follow two business owners through the process.
Meena runs a garment trading business in Surat. She wants a ₹20 lakh working capital loan to stock up before the wedding season. Arjun runs an auto-parts manufacturing unit in Pune. He wants a ₹4 crore term loan to buy new machinery. Both are MSMEs, and both need credit. But, as you will see, lenders look at them in quite different ways.
Key Takeaways
Credit assessment for MSME borrowers is how a lender decides whether your business can repay a loan, and whether it is likely to.
MSMEs are harder to assess than salaried borrowers because their income is uneven, their records are often patchy, and many have little credit history.
Most lenders still judge borrowers on the “5 Cs”, which refer to Character, Capacity, Capital, Collateral and Conditions.
The criteria to judge MSME loan creditworthiness are shifting from collateral to cash flow, with GST returns, bank statements ,and digital payments carrying more weight.
Your documents need to tell the same story. When GST, bank, and ITR numbers do not match, approvals slow down or stop.
What Is Credit Assessment for MSME Borrowers?
Credit assessment for MSME borrowers is the process lenders use to decide whether a micro, small, or medium business should get a loan, how much, and on what terms. It comes down to two simple questions. Can the business repay? And will it?
The first question is about money: income, expenses, and existing debts. The second is about behaviour: has the business repaid on time before, filed its taxes regularly, and kept its records honest?
Think of it like a landlord checking a new tenant. The landlord wants proof of steady income and a good track record. A lender wants the same thing, only it reads your bank statements and GST returns instead of calling your references.
Is Your Business an MSME?
Your category matters for MSME loan eligibility, because it decides which government schemes and loan products you can apply for. Here are the limits that have applied since 1 April 2025:
Category
Investment in Plant and Machinery (up to)
Annual Turnover (up to)
Micro
₹2.5 crore
₹10 crore
Small
₹25 crore
₹100 crore
Medium
₹125 crore
₹500 crore
Why Is It Harder to Assess an MSME Than a Salaried Borrower?
A salaried borrower is easy to read. The same amount lands in the account on the same date every month, and a salary slip confirms it.
Meena’s account, like any other business owner, looks nothing like that. Sales shoot up in the weeks before Diwali and the wedding season, then slow to a trickle during the monsoon. One month she deposits ₹12 lakh. Two months later, barely ₹3 lakh. Is her business struggling, or is that just how the garment trade works? The lender has to figure that out.
This is a big reason MSMEs struggle to get the credit they need. A SIDBI report puts the MSME credit gap at about ₹30 lakh crore, roughly 24% of total demand. Interestingly, the same report found that only 18% of MSMEs use digital loans, even though more than 90% accept digital payments.
How Do Banks Assess MSME Creditworthiness? The 5 Cs, Explained Simply
Most lenders, from big public sector banks to small NBFCs, still start with a simple framework called the 5 Cs of credit. Here is what each one means, and how it plays out for our two borrowers.
The C
What the Lender Wants to Know
What it Looks Like in Practice
Character
Do you pay on time?
Meena’s personal credit report shows a credit card paid on time for five years. That is a good sign.
Capacity
Can your income cover the new EMI?
The lender checks whether Arjun’s yearly profit can comfortably cover the repayments on his ₹4 crore loan.
Capital
How much of your own money is in the business?
Arjun has put ₹1.5 crore of his own savings into the factory. Lenders like owners with skin in the game.
Collateral
What can the lender fall back on if things go wrong?
Arjun can pledge his factory land. Meena has no property to offer, so she may need a guarantee-backed loan.
Conditions
How healthy is your industry, and what is the loan for?
Auto parts are tied to car sales. Garments are tied to festive demand. Both are steady, but both have bad years.
Documents and Data Lenders Check for MSME Loan
The exact document list varies by lender and loan size, but these are the usual documents required for an MSME loan:
Document
What It Tells the Lender
Common Slip-up
KYC and Udyam registration
Who you are and that your business is a registered MSME
Udyam details not matching PAN or GST records
GST returns
Your sales, filing discipline and business vintage
Late or skipped filings
Bank statements (usually the last 6 to 12 months)
Real cash flow, existing EMIs and bounces
Submitting only the account with the best balance
Income tax returns
Declared profit over the last two or three years
Profit in the ITR far lower than sales suggest
Financial statements
Profitability, debt levels and working capital health
Unaudited or outdated accounts
Credit reports
Past repayment behaviour of the business and its owners
Never checking the report before applying
Existing loan statements
How much you already owe, and to whom
Leaving out a loan that later shows up anyway
How Lenders Cross-Check Your Documents?
Here is the part most owners never see. A lender does not just read each document on its own. It lays them side by side and checks whether they agree.
Say Meena’s GST returns show ₹80 lakh in sales last year. Her bank statements, though, show only ₹50 lakh coming in. Where did the other ₹30 lakh go? Maybe some customers paid in cash. Maybe the money landed in a different account. Whatever the reason, the lender will ask, and her loan will wait until she answers.
Lenders follow a few simple rules when they cross-check for a GST-based business loan:
Your documents should tell the same story. Sales in your GST returns, money in your bank account and profit in your ITR should broadly line up.
Your EMIs should leave breathing room. Existing loans plus the new one should not swallow the money you need to run the business.
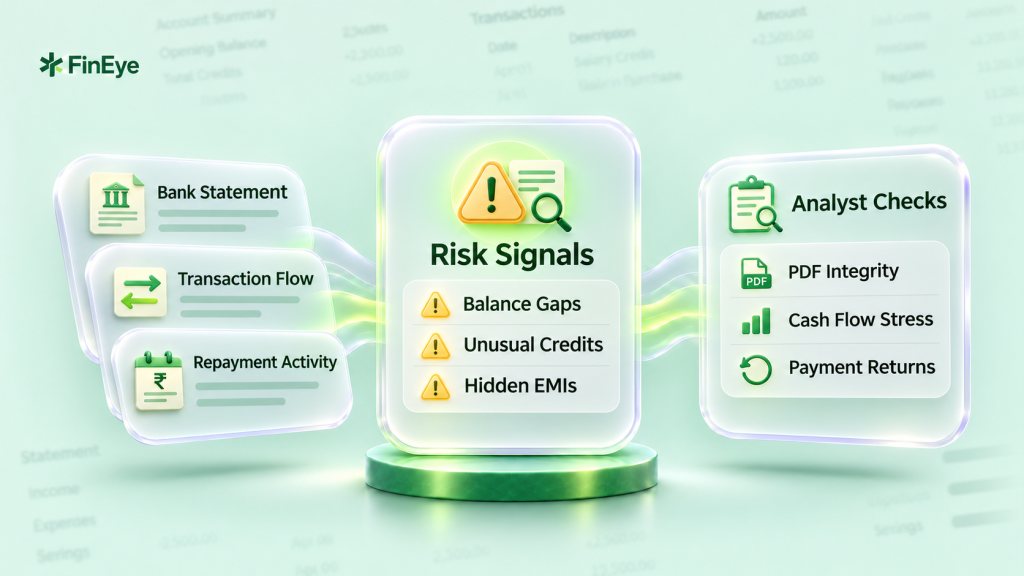
Bounced cheques and failed EMIs leave a mark. Even one or two can raise questions about how you manage cash.
Sudden balance jumps raise eyebrows. A large deposit just before you apply, which leaves soon after, looks like window dressing.
Personal spending blurs the picture. When household bills run through the business account, the lender cannot tell what the business really earns.
Checking all this by hand takes time, often days per application. That is why more lenders now use AI tools like FinEye, which read financial documents such as bank statements and GST returns, match the numbers across them, and flag anything that does not add up. What once took a credit team days can now be done far quicker, and with fewer things slipping through.
Take Meena’s case. A bank statement analyser can sort a year of her transactions into sales, supplier payments, EMIs and personal spends in minutes, and spot any bounces along the way. A GST analyser can then line up her filed sales against those bank credits, so the ₹30 lakh gap shows up straight away instead of weeks into the process.
Common Reasons MSME Loan Applications Get Rejected
Most rejections are not about the business being bad. They are about the lender not being able to see clearly that it is good. Wondering why MSME loan applications get rejected? The usual reasons are as follows:
Numbers that do not match across GST returns, bank statements and ITRs
Irregular GST filing, which makes your sales record look unreliable
Frequent bounces of cheques or EMIs
Too much existing debt for your current income
A short business history, with too little track record to judge
Incomplete documents, or ones that are outdated
A weak credit history, for the business or for its owners
How to Improve Your Chances of Getting Approved?
The good news? Almost everything on that rejection list is in your control. Here is where to start:
File GST on time, every time. Your filing record is now one of the first things a lender checks.
Keep a separate business account. Let it show only business money, so your real earnings are easy to see.
Move more sales to digital payments. UPI, card and bank transfers leave a trail. Cash does not.
Keep your ITR in step with your GST. Large gaps between declared sales and declared profit invite questions.
Check your credit report and CMR before you apply. Fix errors early, not after a rejection.
Register on the Udyam portal. It is free, and it opens the door to MSME schemes and priority lending.
Ask about collateral-free options. RBI rules say banks should not ask micro and small enterprises for collateral on loans up to ₹10 lakh. For larger amounts, loans backed by the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) can also reduce or remove the need for collateral.
Conclusion
MSME credit assessment can feel like a black box from the outside. It is not. A lender is simply trying to understand your business well enough to trust it with money. Arjun gets there through audited accounts and a factory he can pledge. Meena gets there through three years of clean GST filings and a bank account that tells an honest story. Different routes, same destination.
The direction of travel is clear, too. Lenders are relying less on property papers and more on what your records show about how the business actually runs. And as tools like FinEye help lenders read and match financial documents faster, a clean, consistent paper trail is quickly becoming your strongest loan application.
Frequently Asked Questions
What is CIBIL MSME Rank, and what is a good rank?
CIBIL MSME Rank (CMR) is a risk score that TransUnion CIBIL gives to businesses with an existing borrowing history. It runs from 1 to 10, where CMR-1 means the lowest risk. The closer your business is to CMR-1, the better your chances of approval and good loan terms.
Can an MSME get a loan without collateral?
Yes. RBI rules say banks should not ask micro and small enterprises for collateral on loans up to ₹10 lakh. For larger amounts, loans covered by the CGTMSE guarantee scheme can also be given without collateral, though the lender still checks your cash flow and credit history.
How many months of bank statements do lenders usually ask for?
Most lenders ask for the last 6 to 12 months of statements for all business accounts. Some may ask for more, especially for larger loans or seasonal businesses. Sharing statements through anAccount Aggregator can save you the trouble of downloading and uploading them.
Does irregular GST filing affect loan approval?
Yes, quite a lot. GST returns are one of the main ways lenders verify your sales. Late or missed filings make your turnover harder to trust and can slow down or block approval, even if the business itself is doing well.
What is the public sector banks’ new digital credit assessment model?
It is a model that public sector banks began using in March 2025 to assess MSME loans from digital data. Instead of relying mainly on paperwork and collateral, banks check GST filings, ITRs and bank statements shared through Account Aggregators. This allows faster, more data-driven loan decisions.
 November 5, 2026
 10 min read